Understand SSF Contribution Rates: Employee vs Employer
Nepal’s Social Security Fund (SSF) Contribution Rates define the monthly contributions for employers and employees. Many companies join the fund without fully understanding these contribution percentages. This lack of understanding can lead to payroll errors, incorrect deductions, and inaccurate monthly filings. Employees often notice SSF deductions on their payslips without understanding the employer’s contribution. They may also lack clarity about how the fund uses these contributions.
Fast Onboarding
Secure Cloud-Based
Employee Self-Service
31% Total Contribution
11% from Employee
4% Protection Schemes
20% from Employer
This is important not only because it is a requirement, but also because it can impact retirement savings, health and wellness benefits, and other long-term rewards based on regular contributions. With more companies moving to formalize payroll procedures and systems to register under theSocial Security Fund system, knowing these rates, rules of allocation and reporting timelines become vital for HR staff and for the employees who will be relying on these benefits later.
What the Social Security Fund Actually Covers
The Social Security Fund is a group of employee benefit schemes all funded by the same contribution. Registered employers now make payments via a single system for the three components of provident fund,gratuity and insurance. This fund provides protection for retirement payments, medical treatment, insurance against accidents and payments to dependents, among other things.
These benefits were previously available in a variety of different and inconsistent employer-provided systems before this consolidated system. Some companies managed provident funds properly but did not provide insurance coverage. Other companies provided insurance but did not manage provident funds properly. The SSF system created a uniform approach for all registered employers. This approach helps workers receive similar benefits, regardless of their employer. Workers must continue meeting the required registration and contribution obligations.
How Employers and Employees Share Contributions
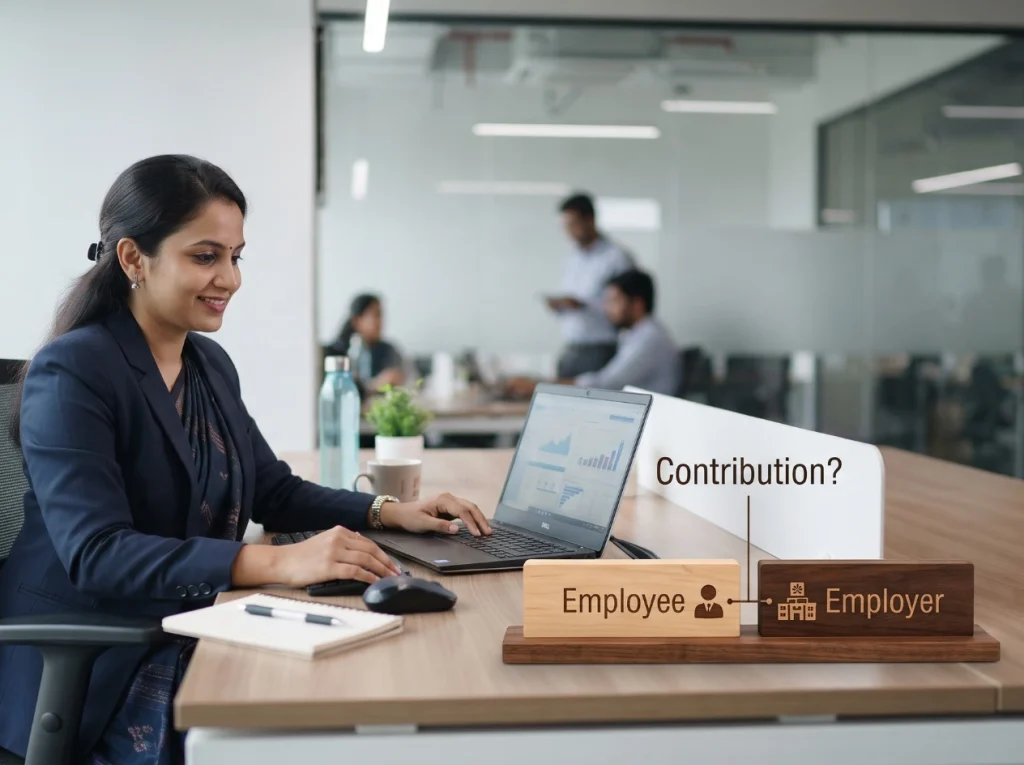
The employer and employee share the SSF contribution based on the employee’s basic remuneration. The employee contributes 11 percent, while the employer contributes 20 percent. Together, these contributions equal 31 percent of the employee’s basic salary. The Social Security Regulations establish these contribution rates. Employers carry a larger contribution because the SSF operates as an employer-sponsored benefit system. Workers do not bear the full cost of their SSF benefits.
These percentages are based upon basic salary and not gross salary, which can be confusing to employees who check their payslip deductions and compare them with their total salary. House rent, Dearness or Travel is not included in this calculation. AllHR teams should use the same percentages for all eligible employees as using different percentages for different departments or branches could lead to discrepancies if audited or if employees ask about their percentage. Rates and thresholds are subject to the authority of the official, so it is always best to check current rates and thresholds on the official portal of the Social Security Fund before setting up payroll as they can change over time.
How the SSF Allocates Contributions
The combined contributions do not go into one undivided account. Instead, the SSF divides the 31 percent among four designated sub-funds. Each sub-fund supports a specific category of benefits. The old-age pension receives the largest share at about 28.33 percent. This share includes provident fund savings from both employers and employees. It also covers a separate gratuity component. The remaining schemes support medical and health benefits, accident and disability coverage, and dependent family benefits. Medical and health benefits receive about 1 percent. Accident and disability coverage receives 1.4 percent, while dependent family benefits receive 0.27 percent.
This scheme applies employee contributions to several benefits instead of one lump-sum retirement benefit. Understanding this breakdown helps employees recognize the benefits available to them. These benefits extend beyond savings withdrawals and include medical claims and insurance support. Employees can access these benefits when they meet the required conditions. The scheme also sets a salary limit for contribution calculations. Employees earning above this limit contribute only on the specified amount. They do not contribute on earnings exceeding the applicable salary limit.
Registration Requirements Before Contributions Begin
Employers are only required to formally register with the Social Security Fund to pay contributions. There is a business registration process that involves providing business documentation, employee information, andpayroll data prior to processing monthly contributions properly. Employers that have postponed the registration are likely to build up a pile of contributions that are not paid, which can get more complicated for the employer later in the process.
In addition, each employee must be registered with the fund (usually at the same time or soon after the employer) for them to be part of the fund. If this individual enrollment isn’t in place, they will not be able to see the contribution credits correctly attributed to the right employee’s account even if the employer pays on time. Many small businesses are caught off-guard when enrolling for the first time in their compliance cycle because of this two-part registration requirement.
Common payroll mistakes that relate to contribution rates.
Many HR departments come up with their contributions by taking a percentage of gross salary rather than fixed remuneration, which can lead to over-payment or under-payment for an entirepayroll cycle. It is hard to spot this error until an audit or employee complaint leads to identifying the error, then having to fix a months-long period of inaccurate contributions.
Another common problem is that sometimes a company files the return one month and doesn’t file it the following month. Others may fall behind on payments or miss several months when they experience cash flow issues, and then realize that they are accruing penalties and not covering all of the employee benefit eligibility requirements. Affected employees have the potential to miss out on some benefits when they require them due to unexplained gaps in their contribution history.
Other problems arise when employees are misclassified. Not all categories of workers would need to have the same treatment of their contributions, and businesses using a blanket approach towards staff which apply the same pattern to all employee categories may end up contributing too much for exempt workers, or too little for those who are exempt and should be fully contributing.
Why Accuracy Here Protects Both Sides
Employers who keep accurate contribution records ensure that they won’t face penalties, audits or be involved in a dispute which can take months to resolve. The consistency of the contribution history in clean records also helps a company’s reputation when it is subject to an external compliance check, as an inconsistent history may raise an immediate concern for the auditor.
This is no less true for theemployees because the final outcome of retirement funds, medical claims or insurance benefits received depends heavily on their contribution history being uninterrupted and correct. An error in calculation can be a small detail at the moment, but can make future claims for benefits more complex years down the road when that employee does need the benefits. When the accuracy of contributions is treated as a continuous focus an afterthought each month will not long-term outcomes will be in everyone’s best interests.
Completing SSF Employer Registration Without Delays
Employers understand the SSF contribution rates after completing their registration under the SSF system. Registration requires businesses to provide company details and confirm employee information. Employers must also establish a compliant payroll system before processing contributions. Completing the required paperwork early helps businesses avoid contribution backlogs and potential penalties. Delayed enrollment can create compliance issues once the company starts hiring.
Frequently Asked Questions (FAQ)
One common mistake when creating a payroll is to include contributions on top of the basic remuneration instead of on total gross earnings.
No. The employer's contribution is 31 percent, with 11 percent from the employee and 20 percent from the employer.
Failure to participate can lead to penalties and gaps in an employee's benefit eligibility, especially in relation to benefit eligibility based on a history of participation.
Yes. It is compulsory to register each individual employee separately from the employer for contributions to be credited properly to each employee's account.
Yes. It can be difficult to ensure compliance if a uniform rate is applied to all workers, as some classifications may be eligible for different or more favorable treatment or have different treatment under pay rules.
Trusted by 1600+ Organisations
Why to Choose Hajir?
Efficiently manage payroll, leave, and communication to streamline
HR processes and enhance employee satisfaction.
HR processes and enhance employee satisfaction.
Cost Effective Solution
Automates manual processes, saving businesses on administrative costs and resources.
Cloud-Based Accessibility
Access your data anytime, anywhere—perfect for remote and hybrid work environments.
Customizable Features
Adaptable to your business needs, with features like shift scheduling, WPS compliance, and custom reporting.
User-Friendly Interface
Designed for simplicity, ensuring a smooth experience for both HR teams and employees.
Data Security & Compliance
Robust security measures protect sensitive employee information, meeting regional compliance standards.
Quick Implementation
Hassle-free setup and onboarding process that gets your HR operations up and running in no time.
Scalability
Whether for small businesses or large enterprises, it can scale to meet the needs of any organization.
Boost Employee Productivity
With automated processes and real-time updates, Hajir helps you focus on what matters most—growing your business
12h/6d Customer Support
Dedicated support ensures that your HR operations run without a hitch.
Download the App and Get Started
Get the app from Play Store and App Store